
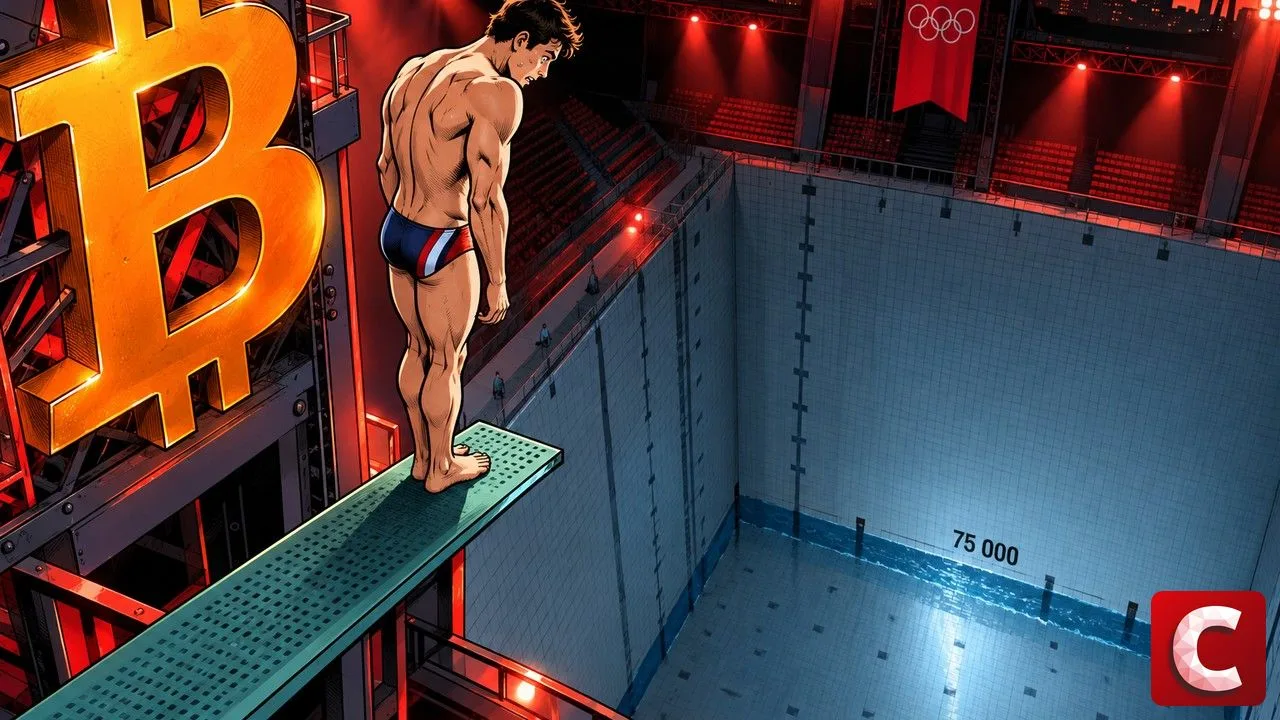
Bitcoin options carrying $15.9B in notional settle on Deribit this Friday at 08:00 UTC, the venue’s largest quarterly expiry of the year. That single print covers 37% of the $43.5B sitting in total BTC open interest. The book leans hard toward buyers, with a put/call ratio of 0.69. Max pain sits at $75,000, more than ten thousand dollars under spot.
Key Takeaways
- $15.9B in Bitcoin options settles Friday at 08:00 UTC on Deribit.
- A 0.69 put/call ratio shows positioning built for higher prices.
- Max pain at $75,000 sits far below where the market trades.
Get an AI Summary of This Article
ChatGPTHow Much These Bitcoin Options Actually Carry
Friday concentrates $15.9B of notional into one settlement window. Ether options expiring at the same hour carry $2.1B, roughly seven times smaller.
The number lands harder against the rest of the book. Those $15.9B represent 37% of the $43.5B Deribit reports in total Bitcoin open interest. More than a third of the book unwinds in a single morning.
Strike distribution updates live in the public metrics dashboard the venue refreshes through the session. The single heaviest strike of the whole expiry sits at $70,000.
That $70,000 level dates from a market trading far lower. Spot touched $86,454 this week, closing a run Cryptonomic covered when Bitcoin held $86,400 on ETF flows and cheaper oil.
A quarterly expiry of this size differs from the weekly cycle in the depth of what it holds. Many of these positions opened months earlier, through the summer climb. Weekly Bitcoin options mostly hedge a dated event, while quarterlies carry positions opened months earlier.
A Book Built for Higher Prices
A put/call ratio of 0.69 means calls outnumber puts by a wide margin across these Bitcoin options. Luuk Strijers, chief executive of Deribit, frames the setup as positioning built for higher prices.
The breakdown says more than the ratio. Of $9.4B in call notional, 55% currently sits in the money, much of it accumulated during the third straight monthly gain the market had just posted. Puts largely expire worthless at these levels.
Across the full $15.9B book, roughly 33% settles in the money. Two thirds of this expiry pays nothing on Friday morning, which is ordinary for a quarterly print.
Call blocks cluster at $85,000, $90,000, $95,000 and $100,000. Jean-David Péquignot, chief commercial officer at Deribit, reads that spread as a layered support structure rather than one pivot level.
On the downside, put floors anchor at $60,000, $70,000 and $75,000. Those three marks map where put sellers would absorb paper if the market breaks lower.
The spacing between those bands matters as much as the levels themselves. Calls sit stacked in five thousand dollar steps above spot while the put floors sit ten to twenty thousand below, which leaves a wide stretch of strikes where very little open interest has to be defended either way.
This positioning accumulated through the summer climb, a streak last seen in 2012, which explains much of the call buildup on upper strikes.
Also on Cryptonomic:
- Bitcoin Holds $86,400 on ETF Flows and Cheaper Oil
- CryptoQuant Sees Bitcoin Rising 3x to 5x This Cycle
- Bitcoin Streak Reaches a Third Month, Last Seen in 2012
What Max Pain at $75,000 Means for a Portfolio
Max pain marks the settlement level where option holders lose the most. For this expiry it sits at $75,000, against a market that traded near $85,500 on Monday and under $84,000 by Thursday morning.
The gap runs past $10,000. A max pain that far from spot mostly says the market climbed faster than the book repriced, an acceleration on display when the Bitcoin price hit $87,000, its highest since January.
Max pain theory holds that spot drifts toward that level into settlement. It assumes market makers carry enough weight to pull price there, an assumption that is hard to verify when the underlying trades around the clock on venues with no options book at all.
The documented mechanical effect is smaller. As expiry approaches, covered call sellers adjust delta, which amplifies moves in both directions through the final hours. That churn usually fades once settlement clears.
Size alone also changes the arithmetic of that hedging. When a third of a venue’s open interest rolls off at once, the dealers carrying the other side rebalance in blocks rather than in trickles, and the order flow that follows says more about inventory management than about anyone’s view on price.
Friday’s calendar adds noise on top. US durable goods orders, the Michigan sentiment print and CME futures settlement all land inside the same window, which makes any price move hard to pin on Bitcoin options alone.
For an investor holding spot BTC, the expiry works as a thermometer of how everyone else is positioned. A book at 0.69 put/call leaves thin protection in place if the market rolls over after Friday.
Cascading liquidation stays the live risk. The market showed that in spring when Bitcoin fell below $73,000 alongside a billion dollars of liquidations, on a book that also leaned long.
Follow the story on Cryptonomic.